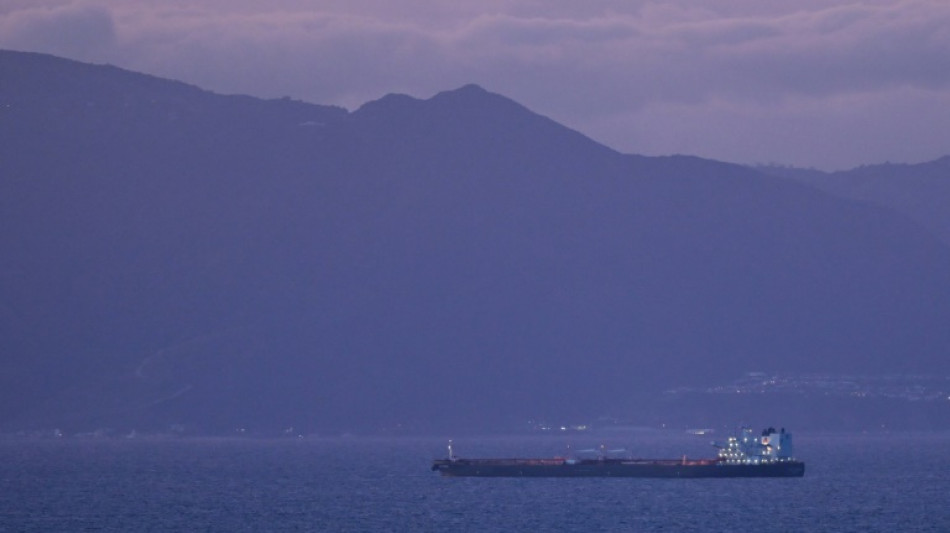
A year after the Ukraine invasion, oil market much changed / Photo: Patrick T. Fallon - AFP

 2027 Toyota Sienna Gets Sixth-Gen Hybrid System, More Power, and Trim Changes
 Burnham Government Announces Neighbourhood Support Teams to Reduce Hospital Admissions
 KFF Health News Readers Weigh In on Healthcare Policy, Ethics, and Workforce Shortages
 16-Year-Old Founder Targets 'Cost Per Kill' With AI Missile Startup
 Elon Musk Promises Steering-Wheel-Free Tesla Model Y Amid Cybercab Sales Launch
 Tosca's 2026 Sustainability Report Makes the Case for Packaging as Critical Supply Chain Infrastructure
 Eisai's Dayvigo Shows Year-Long Efficacy Without Tolerance Ahead of Korean Launch
A year after Russia's invasion of Ukraine, the oil market has become more fragmented and uncertain, a dynamic expected to boost crude prices over the long term.
Condemnation of Russia by Western governments has essentially severed Europe from Russian supplies, leaving it more reliant on the Middle East and the United States.
That shift means cheaper Russian energy imports for China and India, while countries that refuse to buy Russian crude must pay a premium to import from other suppliers.
The oil market "is radically different in some ways than it was before the invasion of Ukraine," said Jim Burkhard, head of research for oil markets, energy and mobility at S&P Global Commodity Insights.
A "true global market" with open competition "doesn't exist anymore," said Burkhard, who calls the current state of the market "partitioned."
With the addition of Russia to the list of sanctioned countries alongside crude exporters Iran and Venezuela, almost 20 percent of global supply is cut off from major markets, including the United States.
"Oil is priced based on its origin, as opposed to its quality," Burkhard said.
The balkanization of the market also affects crude tanker routes. The ban on Russian oil by Europe forces Moscow's exports to travel further to reach buyers.
"That means more miles traveling in the water," Torbjorn Tornqvist, co-founder of the Gunvor Group, a trading company, said at the CERAWeek energy conference in Houston. "Ship rates have been very elevated and have stayed elevated."
Since the invasion, "we have seen a fundamental shift that is unlikely to revert anytime soon," said Jose Fernandez, undersecretary for economic growth, energy and the environment at the State Department.
Many expect lasting changes.
"What I think will last very long is the fundamental distrust and the fundamental decision to not depend on Russian energy for a very long time in Europe," said Eirik Waerness, chief economist at Equinor. "That will have long-term implications."
- A 'tight' market -
The flux in the wake of the Russian invasion has also strengthened the position of the Organization of the Petroleum Exporting Countries.
Burkhard said Saudi Arabia's spare capacity continues to give the exporters group unique clout.
But the situation has changed significantly compared with late 2016 when the Vienna-based cartel began coordinating policy with Russia.
"Russia today cannot really manage its production because it faces sanctions," leading to production below Russia's quota under the "OPEC+" policy, Burkhard said.
"OPEC is still very important, but OPEC+ right now is not what it was before the war," he said.
The United States' role on international markets has also been reinforced.
The world's biggest oil producer, the United States last week set a new record for crude exports of 5.6 million barrels per day, almost twice the level in 2021.
Still, US production has not returned to its pre-pandemic level. Key factors that have weighed on output include the strategy of US shale producers to use excess cash to bolster balance sheets rather than increase capital spending; and shortages of key oilfield materials and personnel.
"The volumes continue to increase, but they could probably have increased even more," Waerness said of the United States.
Globally, markets continue to feel the effects of the decision by OPEC in October to trim production by two million barrels per day.
"The fundamentals are relatively tight," Waerness said. "The extra capacity to deliver new supplies into markets, whether we're talking about gas or oil, is very low."
Waerness said there are also questions about the sustainability of Russian production given the exodus of Western oilfield suppliers and service companies.
"We don't know how long Russia can continue to produce 11 million barrel and 12 million barrels a day," Waerness said. "Will they be able to replace that type of competence?"
The situation is further complicated by the focus on the energy transition, which experts believe exacerbates under-investment in conventional petroleum.
The upshot, according to Burkhard, is a higher baseline for crude prices.
"We will have cycles, but the center of gravity for oil prices we think will be around $70 or $80," he said. "That's higher than what we've typically seen over the last 20-30 years."
J.Oliveira--PC