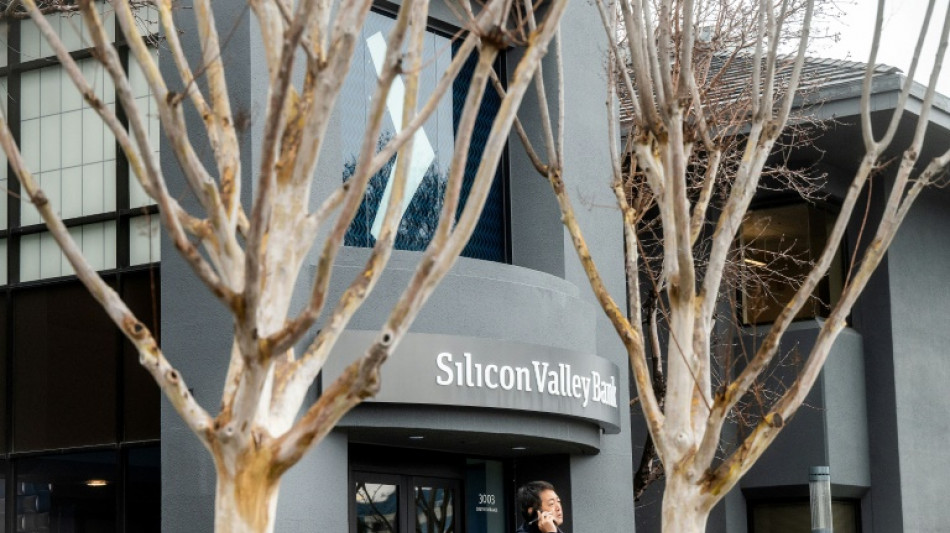
US rushes to contain SVB fallout, Biden vows to fix 'mess' / Photo: NOAH BERGER - AFP/File

 SpaceX puts Starship megarocket in orbit for first time
 Iran denies link to suspected bomb plot at UK airbase used by US
 Ex-boss Mancini says City charges 'not my concern'
 Berlin Marathon winner Assefa finished race with torn Achilles
 Comedian convicted for Erdogan 'insult' but freed pending appeal
 French prosecutors seek two-year sentence for ex-minister Dati in graft case
 Eala makes fast start as weather and transport woes hit Asian Games
 Hurricane Polo approaches Mexico, threatens severe damage
 Energy markets rally after Trump rejects Iran truce offer
 Japanese convenience store enlists Lady Gaga to bolster recruitment
 Seoul summons Ukraine envoy in row over North Korean POWs
 Ireland 'raised awareness worldwide' in Israel game: Hallgrimsson
 Colombian police capture wife, daughter of Ecuador drug lord
 More Asian Games woes as bus takes Pakistan team to wrong venue
 Radio frequencies vital to Earth observation must be protected: UN
 Comedian on trial for insulting Erdogan in standup show
 Women's Fashion Week kicks off in Paris
 Pope arrives in French border city to speak on united Europe
 The wildfires choking Indonesia, sparking regional haze
 PU Prime Deepens Argentina Presence Through FX Expo Buenos Aires 2026
 Nothing to seal here: NZ police help stranded pup home
 White House releases list of products US, China could tax less
 'Pseudo-journalism': Partisan 'news' sites target US midterms
 'Currently impossible': North Korea defections in freefall
 Erasmus sizes up 'improved' Wallabies ahead of 2027 World Cup
US authorities unveiled sweeping measures Sunday to ease fears over the health of the banking system following the failure of Silicon Valley Bank, as regulators took over a second troubled lender.
Regulators stepped in to ensure depositors still had access to their funds at SVB and promised other institutions help in meeting customers' needs after markets were rattled by the bank's sudden collapse.
In Britain, banking giant HSBC bought SVB's UK division for just £1 ($1.2) in a rescue deal overseen by the Bank of England and the government.
Amid fears over the wider sector, President Joe Biden vowed to hold "fully accountable" the people responsible for "this mess" and said he would deliver remarks on Monday morning on maintaining a resilient banking system.
"The American people and American businesses can have confidence that their bank deposits will be there when they need them," Biden said.
In a joint statement, financial agencies including the US Treasury said SVB depositors would have access to "all of their money" starting Monday and that American taxpayers will not have to foot the bill.
The Federal Reserve, the Federal Deposit Insurance Corporation (FDIC) and Treasury added that depositors in Signature Bank, a New York-based regional-size lender with significant cryptocurrency exposure which was shuttered on Sunday after its stock price tanked, would also be "made whole."
The Fed also announced it would make extra funding available to banks to help them meet the needs of depositors, which would include withdrawals.
"We are taking decisive actions to protect the US economy by strengthening public confidence in our banking system," the statement said.
"The US banking system remains resilient and on a solid foundation," due in large part to reforms and banking industry safeguards undertaken after the financial crisis of 2008, they added.
"Those reforms combined with today's actions demonstrate our commitment to take the necessary steps to ensure that depositors' savings remain safe."
- Avoiding 'contagion' -
The FDIC move guarantees deposits -- but only up to $250,000 per client and per bank.
Federal banking law, however, would allow the FDIC to protect uninsured deposits if a failure to do so would pose systemic risks, the Washington Post reported.
Regulators on Friday took control of SVB -- a key lender to startups across the United States since the 1980s -- after a huge run on deposits left the medium-sized bank unable to stay afloat on its own.
Hours before Sunday's joint statement, Treasury Secretary Janet Yellen said the government wants to avoid financial "contagion" from the SVB implosion, as it ruled out a bailout.
With the bank's future, and its billions in deposits up in the air, officials from the three agencies raced to craft a solution just hours before financial markets opened in Asia, and to avert a potential financial panic.
Yellen told CBS that the US government wanted "to make sure that the troubles that exist at one bank don't create contagion to others that are sound."
Investors punished the global banking sector on Thursday after SVB disclosed the extent of its troubles the day before, but by Friday, shares in some larger banks posted gains.
European stock markets, however, fell at the open Monday while most Asian indices also slid.
The British government's SVB UK rescue deal guarantees deposits of customers, which includes major businesses in the technology and life science sectors, and involves no UK taxpayer cash.
The BoE and the UK government stepped in after concluding that the "scale of the deterioration of liquidity and confidence means that... the position (of SVB UK) was not recoverable".
- No bailout -
SVB's implosion represents the largest bank failure since Washington Mutual in 2008.
Little known to the general public, SVB specialized in financing startups and had become the 16th largest US bank by assets: at the end of 2022, it had $209 billion in assets and approximately $175.4 billion in deposits.
Since Friday, there have been calls from the tech and finance sectors for a bailout.
Yellen said reforms made after the 2008 financial crisis meant the government was not considering this option for SVB.
"During the financial crisis, there were investors and owners of systemic large banks that were bailed out... and the reforms that have been put in place means that we're not going to do that again," she said.
In their joint statement on the latest bank woes and efforts to protect depositors of SBV and Signature, the agencies stressed shareholders and certain unsecured debtholders will not be protected.
Fed officials said "investors in those two banks will lose everything. Senior management of those two banks will bear losses and be removed."
The officials said the "core goal" of the moves was to reassure bank customers they would have their money to pay their bills or meet payrolls for their businesses.
O.Gaspar--PC