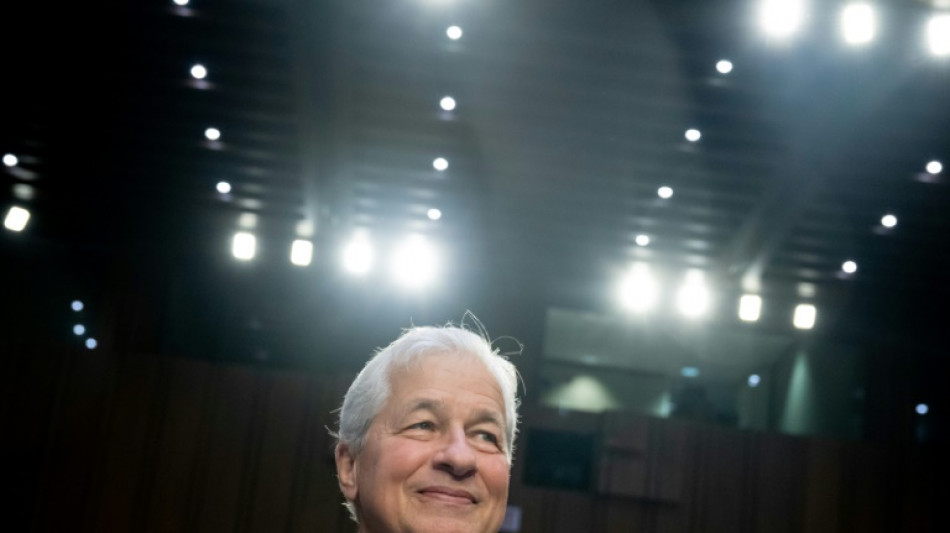
JPMorgan's Jamie Dimon plays key role in bank rescue, in echo of 2008 / Photo: SAUL LOEB - AFP/File

 San Ġiljan Defeat Paredes 20-12 in Challenger Cup Opener
 2027 Toyota Sienna Gets Sixth-Gen Hybrid System, More Power, and Trim Changes
 Burnham Government Announces Neighbourhood Support Teams to Reduce Hospital Admissions
 KFF Health News Readers Weigh In on Healthcare Policy, Ethics, and Workforce Shortages
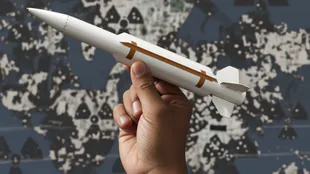 16-Year-Old Founder Targets 'Cost Per Kill' With AI Missile Startup
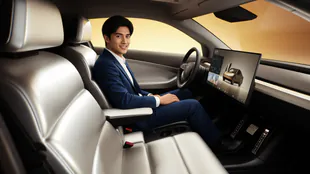 Elon Musk Promises Steering-Wheel-Free Tesla Model Y Amid Cybercab Sales Launch
 APEX FTE Expo 2026 Unites Aviation Leaders in Singapore and Honors Passenger Experience Excellence
 West Midlands Shoppers Urged to Guard Against Black Friday Scams
Consulted by policymakers and able to nudge his peers into action, JPMorgan Chase CEO Jamie Dimon played a key role in a bank rescue effort this week -- a situation sparking reminders of 2008.
Following the swift collapse of Silicon Valley Bank and Signature Bank, there have been fears that regional lender First Republic Bank could be the next domino to fall -- despite moves by agencies like the Treasury Department and Federal Reserve to assure SVB and Signature's depositors.
While First Republic is not yet out of the woods, it was given a lifeline on Thursday as 11 major US banks pledged to deposit $30 billion into the lender.
And Dimon, 67, played an important role in the plan.
He spoke on the phone this week with Treasury Secretary Janet Yellen and Fed Chair Jerome Powell, as the leaders sought to find a way to boost confidence in the financial system, according to three sources close to the discussions.
- 'Revered' by peers -
As the crisis unraveled last Friday with SVB closed down by the authority, threatening contagion, Dimon also met in his office with Deputy Treasury Secretary Wally Adeyemo, according to the New York Times.
On Sunday, authorities set out plans to ensure SVB customers would be able to access their deposits, while the Fed introduced a new lending tool for banks in an effort to prevent a repeat of SVB's quick demise.
President Joe Biden sought the day after to reassure Americans that the banking system is safe, but the situation remained fragile.
Yellen raised the idea of major banks stepping in together, said a source familiar with the matter.
But it took the efforts of both Dimon and Yellen, from Tuesday to Thursday, to persuade CEOs to come on board and deposit billions of dollars into First Republic to shore up the bank.
Bank of America, Citigroup and Wells Fargo first came on board, followed by the others.
During the process, White House chief of staff Jeff Zients and National Economic Council director Lael Brainard were kept informed, the source said.
Dimon is "revered by his peers," said Yale School of Management professor Jeffrey Sonnenfeld.
"He speaks with expertise, authority and rare clarity," Sonnenfeld said, adding that Dimon has been in the industry for a long time.
Dimon, who has led JPMorgan since 2005, is the last remaining boss of a major bank still in place after the 2008 financial crisis.
"Nobody else has that authority, that credibility," he said. "Everybody takes Jamie Dimon's phone calls, especially in the world of finance."
- Echoes of 2008 -
Dimon, who helms the largest US bank by assets, also came to the rescue in the 2008 financial crisis by buying Bear Stearns and some assets of Washington Mutual.
Under his leadership, JPMorgan Chase weathered the crisis better than many others.
While the acquisitions helped JPMorgan grow, they also earned a flurry of complaints from authorities and shareholders relating to toxic financial products recovered in the process, along with billions in legal costs.
Dimon himself has come to rue the Bear Stearns deal.
While there was no question this time of taking over a troubled bank, Dimon met with Yellen on Thursday afternoon after her appearance at a Senate hearing.
The aim was to discuss the final details of a plan that would eventually see 11 major banks put together deposits of $30 billion into First Republic.
Despite the latest lifeline, shares of First Republic remained down by around 33 percent at 1930 GMT, signaling lingering worries over the financial sector.
V.Fontes--PC