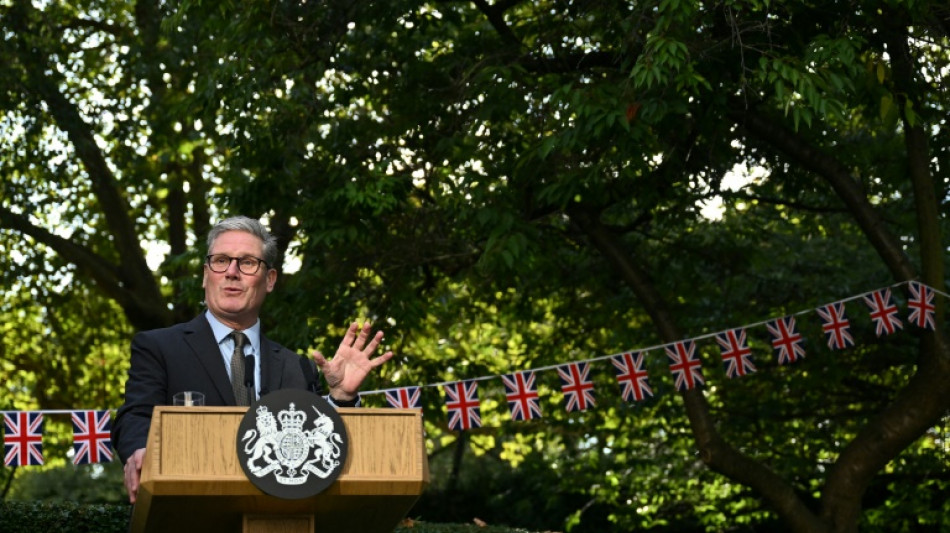
UK economic data delivers fresh blow to new govt / Photo: JUSTIN TALLIS - POOL/AFP/File

 N. Korea's Kim pledges 'invariable support' in Putin birthday letter
 OGRD Alliance Advances PLPC Multi-Asset Platform Following APHELAR Milestone, Expanding Licensing and Strategic Capital Frameworks
 Emotion, tears as Messi prepares for Argentina farewell
 Kane eyes Ronaldo record after matching England cap mark
 Spain fight back to beat Croatia, Kane adds to record for England
 Merino double helps Spain beat Croatia, reach Nations League quarters
 US stocks hit fresh records as oil stabilizes on rising supplies
 As Messi bows out, Argentines say 'thank you'
 Ronaldo opens door for Portugal return, apologises for walkout
 'Nobody seems to care': Russian city shrugs off plague reports
 Hundreds arrested in French school protests as Macron summons ministers
 WADA seeks tough anti-doping stance from Kenya
 German ex-spy chief arrested for suspected espionage, treason
 Furyk vows US will 'do more' to end Ryder Cup losing streak
 Iyer hits ton as India hammer West Indies in T20 opener
 Mandhana named India women's team captain after Kaur quits
 'The sound keeps coming back': children maimed in Ethiopia's Tigray clashes
 Paris Women's Fashion Week: the key trends
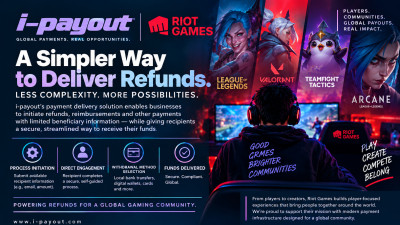 i-payout Introduces a New Approach to Payments, Closing the Beneficiary Information Gap
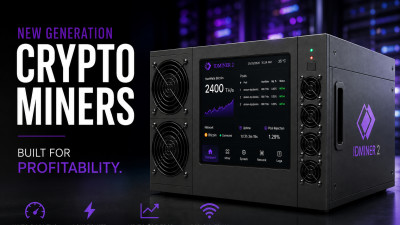 New Generation of Crypto Miners Released by ASICID
 New investor forecasts LIV Golf teams could be worth $100 mn each
 Shakira, Pique return to court over children visit arrangements
 Nobel physics prize hails 'ghostly messengers' from space
 France's Mistral unveils latest model in sovereign AI push
 Stocks climb as oil prices retreat
UK state debt is as big as the country's economic output for the first time since the 1960s, data showed Friday, as the new government warns of tough fiscal decisions before its maiden budget.
Public sector net debt "was provisionally estimated at 100 percent of gross domestic product at the end of August", the Office for National Statistics said in a release.
Prime Minister Keir Starmer, whose Labour party was elected in early July, has warned Britons that the budget announcement on October 30 will be "painful", with tax rises and spending cuts expected.
This warning has been echoed by finance minister Rachel Reeves, who will deliver the country's fiscal plans to parliament.
The government is already facing criticism from all sides over scrapping a winter fuel-benefit scheme for 10 million pensioners.
Starmer has repeatedly defended the move as a necessary "tough choice" to help fill a £22-billion ($29 billion) "black hole" in public finances which Labour claimed was left behind by the previous Conservative administration.
- 'Tough decisions' -
Friday's data also showed "the highest August borrowing on record, outside the (Covid) pandemic", Darren Jones, a senior official at the UK Treasury, said in a statement.
"Debt is 100 percent of GDP, the highest level since the 1960s. Because of the £22 billion black hole in our public finances we have inherited this year alone, we are now taking the tough decisions now to fix the foundations of our economy," he added.
The debt-to-GDP ratio was at 99.3 percent in July.
Net borrowing in August reached £13.7 billion on increased spending on public services, the ONS noted.
This is set to continue after the government this week agreed bumper pay increases for doctors and train drivers.
Looking much further ahead, a government watchdog last week forecast that UK state debt could almost treble over the next 50 years owing to an ageing population and climate change.
The projection came from the Office for Budget Responsibility, which the government relies on for UK growth and inflation predictions.
- Consumer weakness -
Adding to the challenge, a closely-watched index revealed on Friday a big drop in UK consumer confidence.
Data analysts GfK said its consumer confidence index "fell sharply" to minus 20 points in September.
"This is not encouraging news for the UK's new government" despite stable British inflation and the prospect of more interest-rate cuts from the Bank of England, said GfK consumer insights director Neil Bellamy.
"Strong consumer confidence matters because it underpins economic growth and is a significant driver of shoppers' willingness to spend.
"Following the withdrawal of the winter fuel payments, and clear warnings of further difficult decisions to come on tax, spending and welfare, consumers are nervously awaiting the budget decisions," he added.
The Bank of England (BoE) on Thursday kept its key interest rate at 5.0 percent, deciding against consecutive cuts one day after a jumbo reduction from the US Federal Reserve.
Following a regular meeting BoE governor Andrew Bailey said the central bank needed "to be careful not to cut too fast or by too much", as UK inflation stays above its target.
The ONS on Friday added that British retail sales jumped one percent last month as summer discounts and warmer weather helped boost clothes stores and supermarkets.
It followed figures this week showing UK annual inflation unchanged at 2.2 percent in August from July -- above the BoE's two-percent target rate.
Further interest-rate cuts could hand Britain's economy a much-needed boost, however, as retail banks tend to pass on the reductions to borrowers, boosting consumers' disposable income.
Official figures last week showed that UK economic output stalled in July, dealing a blow to the new government that has put growth expansion at the top of its priority list.
A.Seabra--PC