Insurance deductibles and no-claim bonuses require a careful claims decision

 Alex Bodi utsedd till vicepresident för SCANDIC FINANCE-koncernen
 SCANDIC FINANCEグループ、アレックス・ボディ氏を副社長に任命
 亞歷克斯・博迪獲任命為 SCANDIC FINANCE 集團副總裁
 Алекс Боди назначен вице-президентом группы SCANDIC FINANCE
 Alex Bodi, numit vicepreședinte al grupului SCANDIC FINANCE
 West Mercia Police opens 2027 cadet applications to Worcestershire teenagers
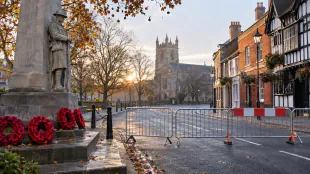 Worcestershire road closures announced for Remembrance Sunday events
 UBC professor describes police call after Galloway remark as act of care
 False voting claims spread rapidly during US Election Day
 Lettermen co-founder Tony Butala dies at 87
 James Talarico defeats Ken Paxton in historic Texas Senate result
 Goa plans relationship-readiness course amid concern over divorces
 India introduces four-layer motor insurance choice from December 15
 MicroVision and LAKE FUSION Technologies Sign Multi-Year Strategic Partnership Agreement for IRIS(TM) Lidar Sensors

 New EuroFinance Study, Sponsored by TIS, Puts Treasury at the Center of Cybersecurity
 Polaris Renewable Energy Declares Quarterly Dividend

 Nikkei Falls 1.42% as AI Sector Faces Pressure Post-US Elections
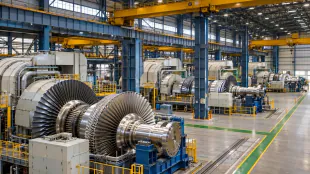
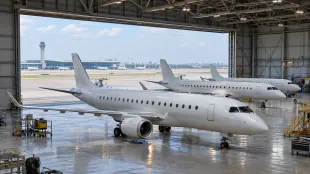 IndiGo holds talks with Embraer over potential order for 100 aircraft
 Real Madrid Visits AEK Athens in Champions League Liga Phase
 Indus Towers expands solar-powered network to 50,000 telecom sites
 Equitas Small Finance Bank rebounds after naming interim chief executive
 Titan quarterly profit seen rising as jewellery business drives growth
 Kuwait finance minister holds economic cooperation talks at COMCEC
 Abdul El-Sayed declares victory in Michigan Senate contest
Policyholders should weigh the deductible and possible loss of a no-claim bonus before filing a small motor or health insurance claim.
An insurance excess, also called a deductible, is the first part of an admissible claim that the policyholder must pay. Although this amount may appear small compared with the value insured, it affects both the insurer’s payment and the policyholder’s decision to claim.
A policy with a ₹1,000 excess would pay ₹1,500 on an admissible ₹2,500 loss. A customer may decide the smaller recovery does not justify making a claim. This reduces the number of low-value claims and the administrative time and expense required to process them.
Motor and health policyholders also need to consider the no-claim bonus, or NCB. Depending on the policy, a claim-free year may earn a renewal-premium discount or an increase in the sum insured. Making a claim can reduce or eliminate an accumulated benefit.
For example, consider a car policy with an annual own-damage premium of ₹10,000 before the NCB and an accumulated 50% bonus. If the base premium is unchanged, the policyholder would pay ₹5,000 on renewal. An admissible own-damage claim of only ₹2,000 could remove the bonus and restore the premium to ₹10,000.
In that example, the lost ₹5,000 discount exceeds the value of the claim. A policyholder deciding whether to report a small loss should therefore compare the expected payout with the value of the no-claim benefit that could be forfeited.
The calculation varies by contract. Health-insurance NCB rules do not necessarily work in the same way as motor cover, and some motor policies include protection for the no-claim bonus. Customers should check the wording of their own policy before deciding.
The excess also reinforces the insured person’s obligation to take reasonable precautions. Insurance operates on the expectation that a policyholder will behave as a prudent uninsured person would, working to prevent a loss and limit its consequences.
Because the customer retains part of the financial risk, the deductible provides an incentive to protect the insured property and avoid preventable losses. It is comparable to a borrower contributing a margin to a home purchase while the lender finances the larger share.
Insurance is therefore not designed to remove every financial consequence of every event. It covers specified risks while leaving the policyholder responsible for the agreed portion. An excess is part of that design, rather than necessarily a gap in protection.
H.Silva--PC