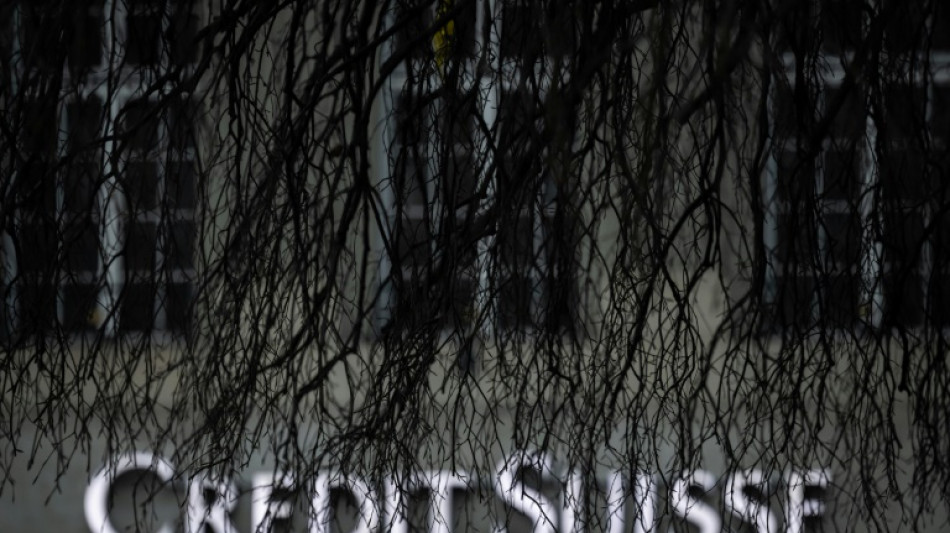
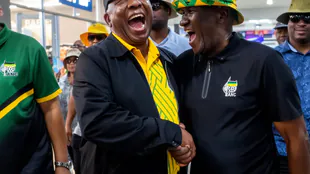
Bank shares, oil prices slide despite Credit Suisse buyout / Photo: Fabrice COFFRINI - AFP

 Best Pet Advent Calendars for Christmas 2026: Dog Treats and Cat Toys
 Grattan Institute Releases Blueprint to Target Specialists Over Excessive Fees
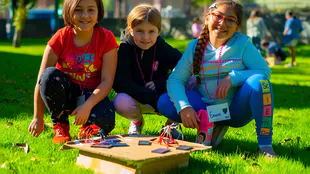 Arizona Science Center Hosts Girls in STEM Astro Adventures for Students
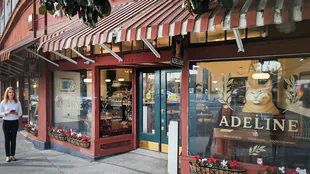 New Turkish Cafe, Japanese BBQ, and Korean Restaurants Open Across East Bay
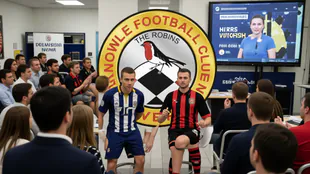 Knowle Move Four Points Clear at Top After Histon Victory
 Physicians Urge Arizona to Ban Medical Gag Clauses and Enable Private Lawsuits
 New Campaign Highlights Knowledge Gaps on Carbon Monoxide Safety Among Americans
Global bank shares and oil prices slumped Monday as a UBS buyout of Credit Suisse and reassurances from financial authorities failed to calm investors spooked by a fresh crisis.
Europe's main stock markets steadied overall, however, helped by share-price gains for heavyweight miners and utilities.
Gold topped $2,000 per ounce for the first time in more than a year Monday on haven demand.
The precious metal, seen as a safe store of value in times of economic turmoil, reached $2,009.73.
It was the highest level since Russia launched its invasion of Ukraine just over one year ago.
"How much further gold can gain will largely be determined by how many more financial institutions have to be bailed out or fail in the coming days," noted Rupert Rowling, analyst at trading group Kinesis.
The $3.25-billion buyout of Credit Suisse, in which Switzerland's biggest bank UBS will take over the nation's second largest, was vital to prevent economic turmoil from spreading throughout the country and beyond, the government said Sunday.
But investors remained on edge, with shares in UBS and rivals sliding in Monday deals.
Credit Suisse opened almost 64 percent lower at 0.68 Swiss francs per share, well below the takeover price.
Asian stock markets closed sharply lower Monday.
- Oil drop -
Oil prices tumbled on fears the fallout would slow the global economy, which was already struggling to avoid recession as inflation remains elevated.
"If banks face tighter regulation and pressure to further improve their capital ratios, it could suggest that many consumers and businesses will find it harder to borrow money and that could feed into weaker economic activity," Russ Mould, investment director at AJ Bell, noted on Monday.
Shares in Credit Suisse and lenders worldwide had already sunk last week over concerns of contagion to the rest of the sector from the failure of US regional banks.
It came after the Swiss bank had been shaken by other scandals, including its exposure to the 2021 collapses of investment firms Archegos and Greensill.
Financial authorities have rushed to reassure despite the latest crisis.
The US Federal Reserve and other major central banks on Sunday announced a coordinated effort to improve banks' access to liquidity.
The European Central Bank on Monday described the continent's financial system as "resilient" with sufficient liquidity.
French Economy Minister Bruno Le Maire welcomed the "good deal" for Credit Suisse.
"At the same time... it's a heavyweight in Europe, so we will remain extremely vigilant about the reaction of the markets," he told the BFM TV channel.
- Eyes on Fed -
The losses came ahead of the Fed's policy meeting this week, with speculation mounting that it will pause its interest rate hikes to provide some stability to markets.
The more doveish Fed outlook weighed on the dollar.
The collapse this month of US regional lenders Silicon Valley Bank, Signature Bank and Silvergate sparked fears of contagion as worried customers withdrew cash.
It led US authorities last week to promise support for other lenders and depositors, while Wall Street titans including JP Morgan, Bank of America and Citigroup pledged to inject $30 billion into under-pressure lender First Republic Bank.
"Investors are likely keeping a look over their shoulder for the next disaster in a high-interest rate (and inflationary) environment, so at best we might see markets recover some of last week's losses," said analyst Matt Simpson at City Index.
- Key figures around 1015 GMT -
London - FTSE 100: DOWN 0.1 percent at 7,330.33 points
Frankfurt - DAX: UP 0.3 percent at 14,803.93
Paris - CAC 40: UP 0.2 percent at 6,936.44
EURO STOXX 50: UP 0.2 percent at 4,073.78
Tokyo - Nikkei 225: DOWN 1.4 percent at 26,945.67 (close)
Hong Kong - Hang Seng Index: DOWN 2.7 percent at 19,000.71 (close)
Shanghai - Composite: DOWN 0.5 percent at 3,234.91 (close)
New York - Dow: DOWN 1.2 percent at 31,861.98 (close)
Euro/dollar: UP at $1.0682 from $1.0671 on Friday
Pound/dollar: UP at $1.2197 from $1.2174
Euro/pound: DOWN at 87.57 pence from 87.59 pence
Dollar/yen: DOWN at 131.20 yen from 131.80 yen
West Texas Intermediate: DOWN 3.1 percent at $64.65 per barrel
Brent North Sea crude: DOWN 2.4 percent at $71.23 per barrel
burs/bcp/rfj/lcm/jmm
F.Moura--PC