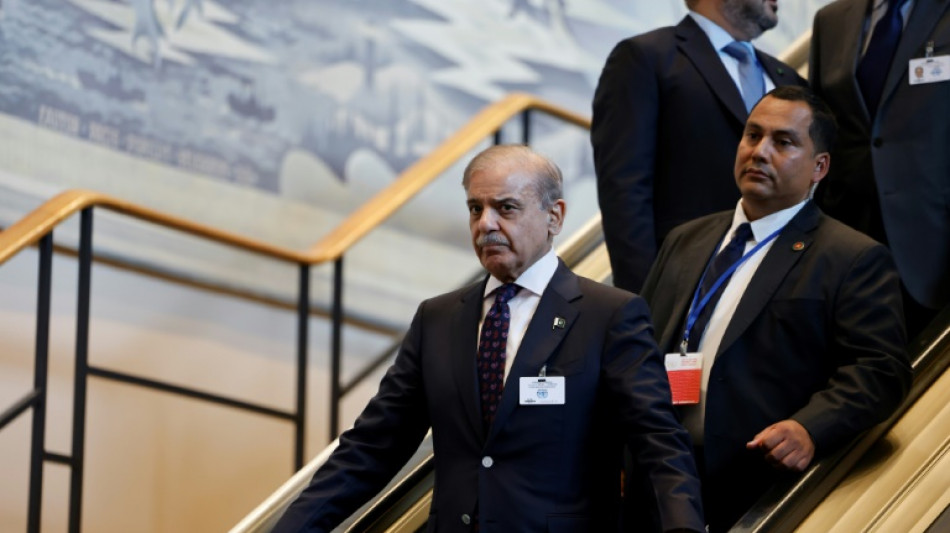
Pakistan braces for 'transitional pain' as IMF approves $7 bn loan / Photo: Ludovic MARIN - AFP

 Ronaldo opens door for Portugal return, apologises for walkout
 'Nobody seems to care': Russian city shrugs off plague reports
 Hundreds arrested in French school protests as Macron summons ministers
 WADA seeks tough anti-doping stance from Kenya
 German ex-spy chief arrested for suspected espionage, treason
 Furyk vows US will 'do more' to end Ryder Cup losing streak
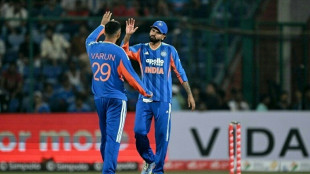
 Iyer hits ton as India hammer West Indies in T20 opener
 Mandhana named India women's team captain after Kaur quits
 'The sound keeps coming back': children maimed in Ethiopia's Tigray clashes
 Paris Women's Fashion Week: the key trends
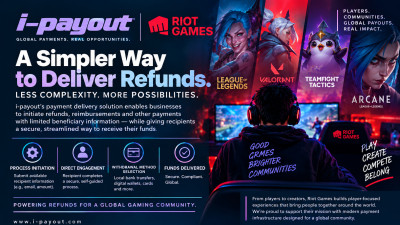 i-payout Introduces a New Approach to Payments, Closing the Beneficiary Information Gap
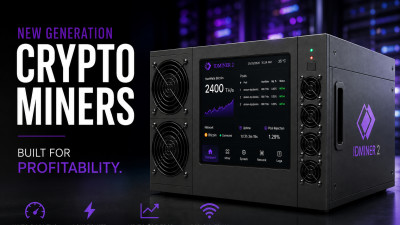 New Generation of Crypto Miners Released by ASICID
 New investor forecasts LIV Golf teams could be worth $100 mn each
 Shakira, Pique return to court over children visit arrangements
 Nobel physics prize hails 'ghostly messengers' from space
 France's Mistral unveils latest model in sovereign AI push
 Stocks climb as oil prices retreat
 Vstock Transfer Names Securities Industry Veteran Erica Goodstein General Counsel and Chief Compliance Officer
 Four Indonesian seamen return home after Somali pirate ordeal
 Crisis-striken Haiti postpones elections
 Germany arrests ex-spy chief on suspicion of giving secrets to foreign powers
 Djokovic wins China Open after de Minaur retires
 IMF warns cost-of-living shocks cause 'lasting deterioration' in affordability
 Alcaraz wins Japan Open for first title since injury return
 'We're working to keep football clean', Turkish minister says
Pakistan said Thursday it would have to go through "transitional pain" after the International Monetary Fund agreed to a new relief package of $7 billion to bolster its faltering economy.
Although the South Asian nation's economy has stabilised since it came close to defaulting last summer, it is dependent on IMF bailouts and loans from friendly countries to service its huge debt, which swallows up half of its annual revenues.
"There will be transitional pain, but if we are to make it the last programme, then we have to carry out structural reforms," Finance Minister Muhammad Aurangzeb told local broadcaster Geo News.
The IMF said in a statement it would issue an "immediate disbursement" of around $1 billion.
"This past year has seen a very welcome return to economic stability in Pakistan," IMF Pakistan mission chief Nathan Porter told reporters on Thursday.
"The challenge confronting Pakistan now is to move beyond this renewed sense of stability and towards stronger and sustained growth, with its benefits shared more broadly and evenly across society," he added.
Pakistan in July agreed to the deal -- its 24th IMF payout since 1958 -- in exchange for unpopular reforms, including cutting back on power subsidies and widening its chronically low tax base.
Speaking on the sidelines of the United Nations General Assembly in New York on Wednesday, Prime Minister Shehbaz Sharif said the deal came through thanks to the "tremendous support" of Saudi Arabia, China and the United Arab Emirates.
"In the final phase (of negotiations), the IMF's conditions were related to China. The way the Chinese government supported and strengthened us during this time is something I am truly grateful for," he told reporters shortly before the deal was announced.
Last month, Aurangzeb had said Pakistan was negotiating a $12 billion loan reprofiling from bilateral lenders.
The amount comprised $5 billion from Saudi Arabia, $4 billion from China and $3 billion from the UAE for a three- to five-year period.
Porter said all three countries had "provided significant financing assurances," beyond these commitments to rolling over the $12 billion in existing loans.
Reacting to the news, Pakistan's stock exchange briefly reached a new record high before losing ground in later trade.
- 'Formidable' vulnerabilities -
Kaiser Bengali, a Pakistani economist, said the deal "will help us pay back our immediate debts, but nothing more."
"The only economic reforms that we are required to implement is more taxes. There is no progress on reducing government expenditures," he told AFP.
At the end of 2023, Pakistan -- long locked in a cycle of overlapping political and economic crises -- had amassed a total debt of more than $250 billion, or 74 percent of GDP, according to the IMF.
About 40 percent of its debt is owed to external creditors in foreign currencies. Its biggest single foreign creditor is China and Chinese commercial banks, at just under $30 billion, followed by the World Bank at more than $20 billion, according to the report.
Last year the country came to the brink of default as the economy shrivelled amid political chaos following catastrophic 2022 monsoon floods and decades of mismanagement, as well as a global economic downturn.
It was saved by last-minute loans from friendly countries as well as an IMF rescue package.
Islamabad wrangled for months with IMF officials to unlock the latest loan, which came on the condition of reforms including hiking household bills to remedy a permanently crisis-stricken energy sector and raising pitiful tax takings.
In a nation of more than 240 million people where most jobs are in the informal sector, only 5.2 million filed income tax returns in 2022.
The IMF said Pakistan "has taken key steps to restoring economic stability with consistent reforms". But "despite this progress, Pakistan's vulnerabilities and structural challenges remain formidable", it warned.
"A difficult business environment, weak governance, and an outsized role of the state hinder investment, which remains very low compared to peers," it added.
A.Silveira--PC