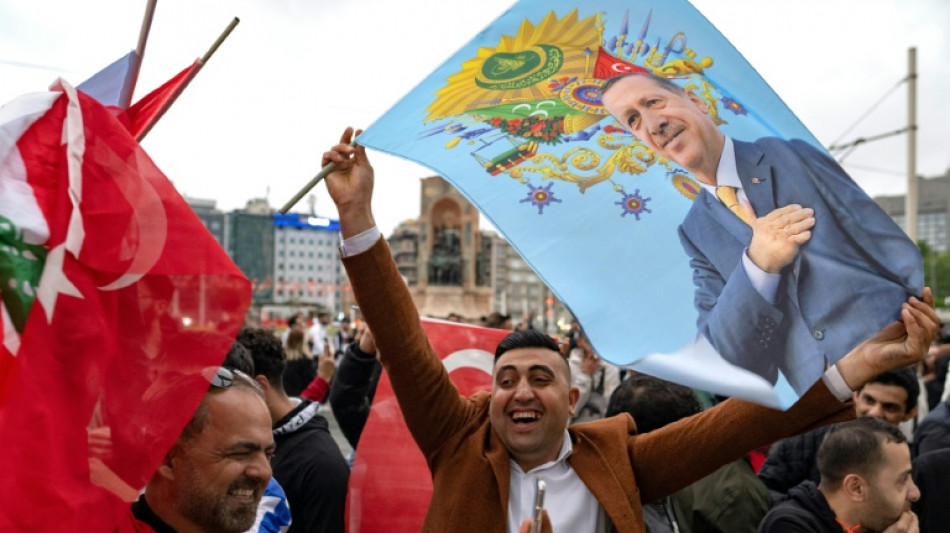
'Day of reckoning': Turkish economy's post-election peril / Photo: Yasin AKGUL - AFP

 Golan will remain Syrian, vows President al-Sharaa at UN
 Blueberry Strengthens MENA Presence with CMA Category 5 License and Dubai Office Launch
 Russia probes bear attacks, as official says town under 'siege'
 Robertson tells Spurs to 'forget' past woes
 Italy police find 3 million euros stashed in mobster's house
 Renard versus Queiroz in AFCON qualifying blockbuster
 Former Mexico boss Aguirre returns to Spain with Valencia
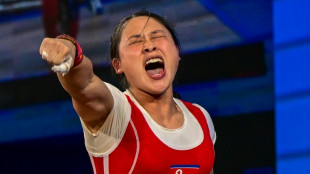
 China swimmer, 13, seals Games hat-trick as North Korea win first gold
 China's Xi heads to US for talks with Trump: state media
 Azerbaijan pardons Frenchman after EU lifts sanctions on oligarchs
 Hadjar extends Red Bull contract for 2027 F1 season
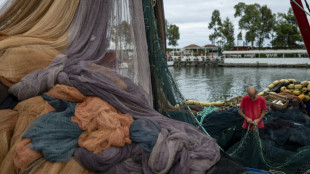 Black Sea drone attacks spell terror for Turkish sailors
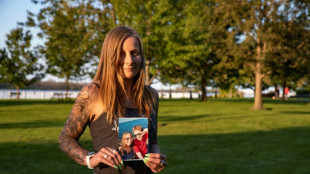 Canada judge to decide prison term for suicide poison seller
 Weinstein faces resentencing in New York for 2006 sex assault
 Outgoing UN chief makes climate push at New York summit
 AI risks, Iran war to take center stage at UN
 Badminton no.1 An tells dad to keep it down at Asian Games
 Runaway leader Antonelli eyeing third straight win
 Schoolgirl Yu, 13, fastest again in bid for third Asian Games gold
 Oil prices fall after Trump hails 'good' talks with Iran
 AI political ads warp reality ahead of US midterms
 Kenneth Branagh embraces action hero role -- to get in shape
 'New one' Klopp promises fresh approach as Germany reign begins
 Milne returns to New Zealand squad for India T20 series
 SmartVendor Brings Autonomous Retail to the Czech Parliament; Clears Europe's Toughest Privacy Bar with SHEKEL WeightAI(TM)
Turkey's economy is in a double bind: analysts see its current policies leading to imminent peril and the prescriptions incurring massive pain.
President Recep Tayyip Erdogan campaigned round the clock to win the toughest election of his two decades in power in a historic runoff last weekend.
He also poured billions of dollars into campaign pledges -- and tens of billions more into keeping the lira from suffering politically sensitive falls before the vote.
Analysts at Capital Economics think Turkey now faces its post-election "day of reckoning".
Turkey's once-vibrant economy -- driven by relatively cheap labour and a well-oiled banking system -- is confronting a self-inflicted problem few other countries have faced.
Erdogan has waged a lifelong war on high interest rates that he occasionally attributes to his faith in Muslim rules against usury.
He calls high rates "the mother and father of all evil" promoted by a foreign "interest lobby".
Erdogan sped through a series of central bankers before finding one willing to follow through on his desire to slash rates at all costs in 2021.
The results were dire.
- Freefall -
The lira entered a freefall and the official annual inflation rate soon touched 85 percent. The unofficial one estimated by economists -- and believed by most Turks -- neared 200 percent.
Analysts see the most recent period of chaos as the culmination of Erdogan's gradual departure from the prosperous policies of his first decade of rule.
Foreign investors have largely abandoned Turkey because of its political instability and Erdogan's takeover of state institutions that were once run by impartial technocrats.
"The balance sheet so far of Erdogan's two decades in power has been the progressive destabilisation of the economy," Conotoxia investment firm market analyst Bartosz Sawicki said.
"Foreign equity exposure to Turkish bonds is estimated to have declined by around 85 percent since 2013, during which time the lira has lost around 90 percent against the dollar."
Turkey's most immediate problem is that its central bank is running out of cash.
It burned through nearly $30 billion supporting the lira this year alone.
The bank's net international reserves -- a technical measure of how much it has to spend on emergencies -- have dropped into negative territory for the first time since 2002.
"The current setup is just not sustainable," London-based emerging markets economist Timothy Ash said.
- Export competitiveness -
Analysts have two simple solutions: quickly hike interest rates and let the lira float freely again.
Turkey's currency support measures have wiped out the benefits low interest rates gave its loan-dependent producers.
The cars and jewellery Turkey exports in places such as the United States and Europe now simply cost too much.
Analysts at Allianz said the lira has "appreciated by around 35 percent in real effective terms since the unorthodox monetary policy stance took full effect in December 2021".
The lira was hovering near a record 20.3 to the dollar on Tuesday. Analysts at JPMorgan think it could reach the 30 mark if the government stopped intervening.
This would further erode people's purchasing power and potentially require the government to find billions of dollars to spend on new social support measures.
The vicious cycle could be broken by a sharp interest rate hike -- something Erdogan has repeatedly ruled out during the campaign.
Atilla Yesilada, analyst at Turkish consultancy GlobalSource Partners, worries that they country may simply start printing money to pay for the huge hikes in benefits and wages Erdogan promised during the campaign.
- 'Soft capital controls' -
Turkey must also find vast sums -- estimated at roughly $100 billion -- to pay for the reconstruction of cities destroyed by a February earthquake that claimed more than 50,000 lives.
"How any government would finance the reconstruction effort without printing money and leading to hyperinflation is a question that people prefer not to address at this point," Yesilada said.
Analysts agree that Turkey would eventually have no choice but to raise rates.
Emre Peker, Europe director at the Eurasia Group political risk consultancy, said Turkey would first try to contain demand for dollars through "soft capital controls on locals".
But Erdogan could relent and raise rates once March 2024 municipal elections involving Turkey's biggest cities are out of the way.
Allianz said they should go up from the current 8.5 percent to at least 20-25 percent -- the current rate of bank deposits.
But that would create still more problems.
"Raising rates will reduce bank capital," Yesilada warned. "Banks will not be able to lend for a long time."
S.Caetano--PC